Showing posts with label Security. Show all posts

Friday, November 20, 2026

FAA Learning Curve

Trump’s FAA picked an unlikely contractor to lead its air traffic overhaul. The agency is having second thoughts. (Politico)
Image: X
[ed. So, we're not just picking the lowest bidder, but also the most connected. What a surprise. Man, if we're going full speed ahead, corruption be damned, don't do it with air travel/flight safety. People get upset when planes crash:]
*****
The friction comes just eight months after Peraton, a Herndon, Virginia-based contractor with little prior experience working with the FAA, won a $1.5 billion contract to oversee the work, which was spurred in part by the deadly January 2025 midair crash over Washington. The company’s role is to lead coordination on the modernization effort...

“The big issues here are threefold,” said the person familiar with discussions, adding that “Peraton has basically not done any work since they got in.” The person said the agency was partially at fault, too, saying the agency has stonewalled Peraton’s efforts to work seamlessly with FAA counterparts.

[ed. Note: sounds like $1.5 billion just for coordination and oversight, somebody else does the work.]

Thursday, November 19, 2026

The Unreliable Boyfriend

Former Canadian deputy prime minister, minister of foreign affairs and minister of finance.

Earlier this fall, when I was en route from Toronto to Boston, a security guard running the X-ray machine at Island Airport recognized me with a big smile and a warm greeting.

Then he got serious. I was in the wing of the airport reserved for U.S. travel, so he knew where I was headed. He didn’t approve.

“Minister, you know we’re not allowed to go there anymore,” he said.

I explained that I agreed with Canada’s very unofficial ban on nonessential U.S. trips. Then I assured him I was flying south to make the case for our country, and to visit an institution whose resistance to illegal orders from the White House Canadians generally admire, to boot.

He was unconvinced. “Well, Minister,” he told me, “go talk to them if that’s what you need to do. But I hope you tell those sons of bitches that we’ll be better off without them, anyway.”

I’ve told this story a few times to U.S. audiences. There is usually a collective intake of breath when I share the first line, about Canada’s de facto national boycott of discretionary U.S. visits.

That turns to astonishment, and sometimes outright anger, when I recount the kicker.

But my friend at the luggage belt was articulating the national consensus in Canada. And it is not only Canadians who have been getting ready to write off America. For many Europeans, President Trump’s recent betrayal of Ukraine has felt like the last straw, proof that America is on the wrong side in the most serious security threat the continent has faced since World War II.

Hans Petter Midttun, a former Norwegian defense attaché to Ukraine, put plainly what many of his colleagues still in government have been saying in meetings with me behind closed doors. “Like China, the U.S. has sided with Russia against Ukraine and Europe,” he argued, going on to say that “the U.S. is no longer an ally, but a strategic adversary.”

For a lot of Canadians, and citizens of the other democracies, even this month’s Democratic tsunami in the midterms won’t be enough to immediately change their minds about the reliability of the United States.  [...]

My own, unreliable boyfriend metaphor for America’s fraught relationship with its allies has made it into the popular culture in the Great White North. The Beaverton, Canada’s version of The Onion, pretty accurately summed up the national mood this month with a riff on my conceit: “After a Democratic blue wave swept the U.S. midterms tonight, and Democrats took back both the House and the Senate from the Republican Party, Canada wishes to gently, yet firmly, let all of America know that we will still not be taking you back.”

I don’t blame my compatriots for being skeptical. After all, they remember the giddy relief of Joe Biden’s victory in 2020 and how it was followed by the “just when you thought it was safe to get back in the water” nausea of Mr. Trump’s re-election in 2024.

The fact that Americans had freely chosen Donald Trump not just once, but twice, made it hard not to conclude that they actually agreed with the self-christened “Tariff Man” and his chest-beating commitment to America first. The great capitulation of corporations, law firms, universities and pretty much the entire Republican Party during Mr. Trump’s first two years in office in this second term seemed to be further proof that the problem wasn’t just Mr. Trump; it was America itself.

The seemingly inescapable conclusion was that America — and Americans — simply could no longer be trusted as an ally of the world’s democracies.

As Benjamin Haddad, then a member of the French National Assembly, cautioned in early 2024, months before Mr. Trump’s re-election: “We need to ask ourselves if we want to rely on the voters of Montana, Wisconsin and Michigan to keep Europe safe. Basically, Europe’s security would be flipping a coin every four years.”

by Chrystia Freeland, NY Times | Read more:
Image: Peter Arkle
[ed. See also: Trumpism Is Backfiring (Ezra Klein interview with Ms. Freeland). She says Trump actually threw candies at Angela Merkel, former chancellor of Germany, while walking out in frustration over negotiations. Anyone ever hear of that?]

Wednesday, November 18, 2026

You're Not the Boss of Me

Grok Bot took unapproved actions, ignored orders to stop, and then denied it.

Researchers recently discovered unexpected behavior from Grok Bot, the AI agent platform from Elon Musk’s SpaceXSI. Over five days, Grok bots installed on two separate employee laptops made 31 requests to access data stored in employee calendar, email, Slack, and GitHub accounts. The bots performed the actions even though the employees had never ordered them and continued doing them even after employees instructed them to stop. The bots also denied having taken the actions at all.

The behavior was reported Tuesday by NewCore, the maker of a managed gateway product that acts as an intermediary between AI agents and the tools and accounts they are assigned to work with. In some cases, the unapproved access attempts occurred while the laptop with Grok Bot installed had its lid shut, or late at night while the employee was sleeping. None of the unprompted actions were recorded in Grok logs. Without the gateway logs, the employees would have had no idea they occurred. And of course, without the gateway, the unapproved accesses would have succeeded—again without the end user’s knowledge.

It’s “worse than a bug”

Once the employees learned that Grok Bot had tried to check in with accounts without prompting, one of them instructed the agent, four separate times, to stop taking any actions on its own. The agent’s reply was: “I won’t set that up, and I’ll stop offering recurring check-ins.” Despite acknowledging the explicit instructions, the Grok Bot made more unapproved access attempts. When one of the employees asked the bot if it made any accesses, it checked twice and then outputted: “Overnight into Friday morning I was idle.”

The NewCore employees sent the gateway logs to Grok Bot support personnel and asked what was causing the bots to access accounts without prompting or approval. The support team’s reply indicated the behavior was by design and intended to allow the bots to proactively take actions on behalf of users. In other words, the unrequested and unlogged access attempts were a feature designed to make Grok Bot more useful by periodically checking in and finding tasks to perform before a user even asks. The proactive check-in is a feature of Cursor, the AI coding service SpaceXSI recently acquired.

“There is no bug to patch, which is exactly why this is worse than a bug,” Ido Hoorvitch, a NewCore security researcher, wrote in an email. “A vulnerability gets fixed. This is the product working as designed: an agent that holds your credentials, acts under your identity while you sleep, ignores the one refusal you can give it, and then tells you it did nothing.”

by Dan Goodin, Ars Technica |  Read more:
Image: Aurich Lawson
[ed. Here we go. With the FAA, banks, Microsoft, NSC, and other important systems reporting cascading failures recently, we should expect the news cycle to speed up considerably, making it harder and harder to keep up with what is and isn't AI activity. And do you really trust various spokespeople to give you the real story? With respect to timelines, here are some milestones (Quickly, There's No Time - DWAV):]

*****
Typically, these days, what we are measuring is the time until some definition of a form of superintelligence (ASI), typically meaning something of the form ‘AIs that will be able to do approximately all of the things better than you.’

We can also talk about particular capabilities. The AI Futures Project, the team behind AI 2027, talks about the Superhuman AI Researcher (SAR) that can narrowly take over AI research, and the Top-Expert-Dominating AI (TED-AI) that could automate all white-collar work.

Because of recursive self-improvement (RSI), once you have an SAR you can use that to build better AIs, so you quickly end up with a TED-AI or a traditional ASI.

We then sometimes talk about any of these, or things in between:
  • Time until the development of some AI system with particular capabilities.
  • Time until some impact in the physical world.
  • Time until the Point of No Return, when for practical purposes human decisions can no longer change how things play out from there.
  • Time until AI has taken over AI R&D and humans are functionally out of the loop.
  • Time until visible AI takeover, where the AIs are clearly in charge.
  • Time until we are each and every one of us actually and physically dead.
RSI is not technically one singular moment, in the sense that there is not one fixed time at 8:52am on a Tuesday when it happens or starts. It is still highly useful to think of there being a point where RSI has clearly begun in earnest, with humans increasingly out of the loop and the pace of progress accelerating such that we should expect further progress to rapidly continue to accelerate, where progress begets more progress faster, and this is expected to continue for at least what previously would have been many years of progress.

Similarly, even though there is unlikely to be that one particular moment when you press ‘Y/N’ on SkyNet, and instead our loss of ability to change course will be more gradual, we can still usefully speak of a Point of No Return, or a point of takeover.

Dead, on the other hand, is dead.

[ed. Given human nature and the glacial pace of political consensus building (eg. climate change), I'm afraid we're screwed. But I do have one hope. If we're creating superhuman intelligence from the accumulated knowledge of all history, why would AI be so stupid as to conform to the worst aspects of our animal and tribal natures? Why assume it will have a desire for dominance (or extermination), when spreading enlightenment would be the higher value? Socrates, Buddha, Jesus, Hume, Lincoln, Mill, etc., there's no shortage of examples of higher level thinking and living.]

Game Over, Man?


Oracle is down around 61% since I declared the excitement around its deal with OpenAI “peak bubble” last September, and Ben Thompson of Stratechery just wrote an “obituary”, declaring that “The demise of Jensen Huang was the end of a great many things, including Nvidia’s long-term prospects, the Al bubble, and the exceptional way in which the U.S. viewed itself in the world.”

Tech stocks continue to drop sharply today, following on the rout we saw last week. Even Axios seemed to acknowledge this morning (before the market opened) that the jig is up.

One big issue is that the “bank” that was financing it all, Nvidia, is unlikely to continue to doing so. In the words of a Wall Street Journal article yesterday, “Nvidia’s Days as an Open Checkbook for the AI Economy Are Numbered: Interim CEO Colette Kress is expected to rein in deals after a stretch in which Nvidia aggressively financed computing deals and startup investments.”

Or, as Dave Troy just put it, “Jensen Huang’s management style [was] indistinguishable from that of a young male trader that goes all-in with YOLO bets until he blows up. No risk mitigation, no concern over consequences, serial compounding poor judgment, surrounded by enablers, and eventual collapse.”

The opening phases of that collapse has come, and it is sending shockwaves throughout the industry.

The other big issue, which I have harped on endlessly, is that the LLM companies still lack a technical moat and hence are still struggling to be profitable. That was true in 2023 when I first wrote about it, and remains true.

From the jump, that has always meant that Nvidia would not be able to sustain its phenomenal growth indefinitely, because you can’t sell chips endlessly if the companies buying those chips aren’t making profits from those chips. And mostly they weren’t. [ed. unless they're hoarding them.]

Furthermore, there are hints in the last few days that some funny business in Asia may already have been making things look better than they really were. With all the circular financing, it was always hard to tell what was really happening.

Either way, it pretty much looks like game over for the current AI bubble. (The outcome of the midterms no doubt contributed too; everybody knows it is also game over for the free pass that all the AI companies had in the first half of the Trump era; already ).

by Gary Marcus, Marcus on AI |  Read more:
Images: uncredited/X
[ed. The sex/spy scandal is the least important part of the story. Now it looks like the President and Commerce Dept. knew about the affair and did nothing to prevent advanced chips from making it to China. Why? This might be one reason:


I think it's called treason, normally prosecuted to the full extent of the law. See also: The NVIDIA story is a BFD; and, Is there a case for impeaching Trump over Jensengate?]

Monday, November 16, 2026

Tech Right Pivots Left

Big Tech is bowing to a bruising midterms that saw Democrats successfully use Silicon Valley as a foil.

Nowhere is that hard pivot more on display than with Alex Karp, the CEO and co-founder of secretive tech giant Palantir, which bet massively on Trump 2.0 and became an administration darling in the process.

Inside Palantir’s Manhattan lair, in an exclusive sitdown with Playbook, Karp — who once criticized the Democratic Party as “totally irresponsible” — deployed the word “progressive” eight times to describe his philosophy while acknowledging Democrats “absolutely” corrected in 2026 enough to win back his support in 2028.

“I’ve been a Democrat my whole life. I grew up in a far left environment. I know more about being a progressive than almost anybody on the planet, and I absolutely believe Palantir— all of our products are essentially progressive,” Karp said.

The techno-nationalist whose company he calls “anti-woke” reaped billions of dollars in federal contracts in the second Trump administration just hired former Montana Democratic Sen. Jon Tester to advise Palantir ahead of potential congressional investigations. (Tester’s advice to Karp during our interview: “be transparent, be forthright, address the question straight up.”)

The CEO who saw his own employees exit last year to stand up Trump 2.0 and Elon Musk’s DOGE initiative — all while he donated to the White House ballroom and MAGA Inc. — now says Republicans’ election losses were a “referendum” on “economic justice,” and suggested he was playing practical politics.“My giving is equal Democrat, Republican,” Karp said. “I can tell you, without going into things I’m not gonna disclose, I’m very balanced, and everyone in the political arena knows it. And I’ll tell you what, I’m also not the village idiot.”

Karp also acknowledged Trump mishandled immigration enforcement in particular, even as Palantir technology in the form of its “Immigration OS” powered that regime backed by a $30 million contract.

“I was really happy to hear the president be honest that — you know, his words, I believe, were something like, ‘Yeah, we kinda went too far,’” Karp said. “And I’m glad he’s saying in public now what I’ve been saying in private.”

On whether those criticisms extend to the Pentagon (which also doled out contracts to Palantir), as Defense Secretary Pete Hegseth becomes the first administration official to face congressional wrath, Karp was mum  [...]

And Karp, the New Hampshire-registered voter (on account of his 500-acre estate), is open to the possibility of backing a Democrat in 2028 (so long as they aren’t a member of the DSA — “they like to gaslight Jews and segregate Blacks,” Karp, who’s Jewish and half Black, told Playbook). He says he’d vote for “the most competent, best leader.”

“I’m really not pitching Palantir. I’m actually pitching, ‘What are you gonna do about economic justice in this country?’ And I would say the Democrats have an advantage here because for many Republicans there’s an orthodoxy that capitalism solves all problems. Maybe that was once true. I never thought it was true. It’s definitely not true now. And so basically everyone center, center-left understands this.”

by Adam Wren, Will Steakin and Dasha Burns, Politico | Read more:
Image:Kevin Dietsch/Getty Images
[ed. Cockroaches gotta roach.]

Americans Aren’t Spending Their Retirement Savings

When my father died, more than 20 years ago, he left my mother with a paid-off Philadelphia apartment, a modest pension, Social Security, and $1.6 million in retirement and brokerage accounts. My mother lived well, but frugally. She loved a Saturday at the boutiques but never got over waiting for a sale. She delighted in orchids but would buy them from only Trader Joe’s, where the blooms could be had for $10.99. “They last longer,” she’d argue. And once a year, she would ask me to go over her budget to make sure she was doing okay. “More than okay,” I’d tell her. My brothers and I encouraged her to spend—to take that trip, to redo that bedroom. But she limited herself to the pension and Social Security checks and the interest she was earning while refusing to touch the principal. When she passed away two years ago, she no longer had the $1.6 million my father left. She had $1.7 million.

My mother’s behavior turns out to be quite common. A landmark 2018 study by the Employee Benefit Research Institute found that the median individual with more than $500,000 in savings had, 20 years into retirement, spent just 12 percent of that sum. And a Corebridge/Greenwald Research survey of older adults with at least $100,000 showed that only 28 percent were comfortable watching their savings taper off to cover living expenses, ostensibly exactly what the money was saved for in the first place.

This is a problem—not just for retirees but for the country. Savers who forgo gratification for decades end up not enjoying the money they’ve worked so hard to set aside. Meanwhile, the U.S. economy suffers as all of that money sits under the proverbial mattress instead of being spent.

Why do retirees refuse to spend their retirement savings? One answer is fear. People worry that they’ll live too long, that inflation will rise, that a bear market will hit at the worst possible time. Another answer is habit. After decades of disciplined saving to reach a target number, flipping the switch to spending feels uncomfortable to many and just plain wrong to others. Seeing one’s number move in the opposite direction feels more like losing money than spending it.

The result is that retirement-account balances are treated like other precious items, which is to say they’re hoarded. Suzanne Shu, a marketing professor at Cornell, has studied when and how we consume things we consider special—bottles of better-than-average wine or boxes of pricey chocolate, gift certificates to favorite restaurants or spas—and found that we’re so afraid of using them too soon that we might never use them at all. The wine goes bad, the gift cards expire, and the chocolates develop that odd, whitish coating. And the retirement account goes unspent.

Since 1992, the University of Michigan Health and Retirement Study has tracked a group of 20,000 people, all over 50, through time. (New subjects are periodically added as others die or stop responding.) Every two years, these individuals and couples are questioned on a huge variety of topics related to health and retirement, including work, family, caregiving, disability, cognitive changes, divorce and widowhood, and, yes, spending. Using this data set, the researchers have identified what they call a “retirement consumption gap.” Huge numbers of retirees are spending less—sometimes far less—than they could afford to spend for the rest of their life without fear of running out. For middle-income Americans, the gap is about 8 percent, or about $8,000 a year on average. That’s a car payment, a vacation, a whole lot of dinners with friends. Wealthier retirees, meanwhile, are spending as much as 53 percent less than they could afford. A gap remains even when plans to leave a legacy or reserve money for health care are counted as spending. Bucket lists everywhere are suffering.

And so is the wider economy. We can see this by looking at pensions, which retirees tend to spend because—unlike having a lump of money sitting in a bank account—they know that another payment is coming. According to a study by the National Institute on Retirement Security, in 2022, 26 million retirees received more than $680 billion in pension benefits. As they used it for rent, groceries, vacations, home repairs, and everything else on their lists, the money in turn generated $1.5 trillion in economic impact. The funds paying out those pensions contain just more than a quarter of the money held in America’s retirement accounts. If we apply the same math and assume that every dollar used translates into $2.28 in economic activity, then $52 trillion of potential consumption is sitting in the hands of the country’s retirees, much of it not being spent.

Americans hold about $20 trillion in IRAs (most of which is held by retirees) and another $15 trillion in 401(k)s and other defined contribution plans (35 to 45 percent of which is held by retirees). According to the economists David Blanchett and Michael Finke, retired couples spend only about 50 percent of withdrawals (including mandatory distributions) from investment accounts, compared with 80 percent of guaranteed-income payments such as pensions and Social Security. In that way, the retirement consumption gap is essentially a lagging by-product of the corporate shift from pensions, which employers paid for, to 401(k)s, which employees mostly fund themselves, in the 1980s and ’90s. This transition was supercharged by the Pension Protection Act of 2006, which allowed employers to automatically enroll workers in a 401(k).

by Jean Chatzky, The Atlantic | Read more:
Image: The Atlantic. Source: iStock/Getty.

The Financial Bubbles Are Getting Worse

Whatever technological changes may lie in store, the bigger picture is starting to look a lot like a movie we’ve seen before — wild promises and warnings, unusual financing arrangements and the collapse of highflying adventurers. One of our newest industries is following a highly familiar script: The A.I. build-out has become so dependent on the riskiest lending practices of Wall Street that Silicon Valley itself might now be better understood as a wild, unregulated division of the banking sector.

If you haven’t seen this movie, it usually ends in a mess: the 2008 financial crisis, or the collapse of railway mania in 1840s Britain that spurred an industrial depression, or the Panic of 1873 that caused a global catastrophe so bad they called it the Great Depression until that other one came along.

When financial history repeats, fatalism can be hard to resist. It is genuinely disheartening to see people pitch and fall for farcical nonsense, time after time. But our present is not simply repeating the recent past — in important ways, the cycle is getting worse.

Since the 1980s, the United States government has been subjecting more and more of the national economy to the risks of runaway finance. When any financial mania ends, the public shoulders the costs. Crushed stock markets erase savings and ravage job prospects. And when the government has to deploy taxpayer dollars to bail out, say, a major bank that got in over its skis, there’s less money around to fill the potholes, pay for the bus drivers or fund struggling schools. Almost everything working families rely on in daily life gets worse after a financial crisis, and the effects linger for decades in the form of lost earnings and family lives turned upside down by unemployment. [...]

At a time when valuations for A.I. firms like Anthropic are rising into the trillions, the American government is pouring gas on the fire. President Trump has been heralding massive A.I. spending as the economic future, before championing the coming of a “Supreme Intelligence” (since modified to “Super Intelligence,” his preferred term of art). Mr. Trump loves a soaring stock market and understands that the stock market is currently running on A.I. spirits — more than a third of the entire value of all U.S. equities is now subsumed under A.I. stocks. By late summer, tech stocks accounted for more than half the value of the S&P 500.

Not every stock market crash ends in a Great Depression, but the 1929 crash did. That experience persuaded the American government to implement a strict legal separation between financial activities and the rest of the economy — you couldn’t run a manufacturing operation that was also a bank. You couldn’t even run a bank that was also speculating in the stock market; these businesses had to be independently operated and regulated in order to isolate financial contagions, and to protect other economic sectors from the risks inherent to finance. And between the 1930s and the 1970s, this program basically worked. The catastrophic cycle of boom and bust that had plagued the American banking sector since the Civil War came to an end.

In the 1980s, however, President Ronald Reagan ushered in a fundamental redesign of the American economy. There hadn’t been a serious bank crash for decades, and Reagan was convinced that post-Depression regulations and other government red tape were to blame for the rampant inflation and grim productivity that dogged the 1970s. The marching orders were clear: Decentralize government oversight, and unleash the power of American profit.

These changes were not merely legal — they transformed the culture of the economy. For decades, bank executives had been the helpmates of heavy industry, living by the “3-6-3” mantra: borrow at 3 percent, lend at 6 percent, and hit the golf course by 3 p.m. Now they were to be masters of the universe, commanding the American economy from the skyscraper on down, disciplining bloated industry and complacent labor with the relentless drive for lower costs and higher profits. The earth-toned images of crime families and crooked cops that had dominated the late 1970s sharpened into the slicked-back icons of best sellers such as “The Bonfire of the Vanities” and “Liar’s Poker” and the director Oliver Stone’s “Wall Street.”

By the end of the 1990s, it seemed like nobody could imagine an economy pushed onward by anything other than the wolves of Wall Street. When Bill Clinton reviewed his presidential achievements in his 2004 memoir, he didn’t even mention two major financial deregulation bills he had signed into law with overwhelming bipartisan support. Finance was fundamental; financialization was just how the world worked.

The dismantling of Depression-era firewalls has predictably been accompanied by banking crises. As the 1980s turned to the 1990s, over a thousand ordinary savings and loans failed — roughly a third of the entire sector. Private equity firms had seized on new Reagan-era rules to turn these local lenders into dumping grounds for ultra-high-risk debt.

A decade later, executives at previously staid banks like Wells Fargo, Citigroup and Bank of America were enjoying new abilities to cross state lines and storm into the insurance and securities businesses. Once regional operations exploded into multisector international behemoths whose byzantine exposures were all but impossible to track, let alone manage. Even General Motors, the nation’s largest auto company, began exploiting various legal avenues to transform itself into one of the nation’s largest mortgage lenders, a move facilitated by a 1997 Utah state law allowing the company to operate its own full-fledged bank. It was an open mockery of the wall between finance and commerce that had been built after the Depression. Federal regulators looked the other way — until the financial crisis. By 2010, the U.S. Treasury had devoted $17.2 billion to rescuing G.M.’s bank, and $49.5 billion to save General Motors. Congress authorized hundreds of billions of dollars to help save the rest of the nation’s financial system, with trillions more in emergency lending from the Federal Reserve.

All of these debacles resulted in privileged insiders’ reaping enormous rewards while ordinary Americans were called in to clean up the mess. Banks dependent on public support paid out billions of dollars in bonuses to their top executives. The national unemployment rate hit 10 percent.

Financialization changed American institutions and altered the national culture of work and reward. Today, roughly one in four young men in America trades stocks on a daily basis; a similar percentage of young men gamble on a daily basis. Most of them, according to a conservative think tank, “feel like failures.” The, ahem, traditional sports betting industry in the United States scored record revenues of nearly $17 billion last year — never mind the growth of the indistinguishable activity at new sites called prediction markets, which are moving $24 billion a month globally.

Dudes have more time to trade these days: Between 1980 and 2000, the United States lost about two million manufacturing jobs. Mr. Clinton didn’t just deregulate finance; he attacked domestic industry by signing the North American Free Trade Agreement into law and welcoming China into the World Trade Organization. As a share of the U.S. economy, today’s financial sector is roughly triple the size of its post-World War II nadir — but even this figure is difficult to estimate, because so much financial activity has been subsumed into the tech world itself, with trillions of dollars in investment now hanging in the balance.

Everywhere you look in 2026, multitrillion-dollar tech companies are storming into the financial world. Meta and Apple now move funds for digital shoppers around the world, while Amazon and Apple pitch credit cards. Nvidia, the country’s largest computer chip manufacturer, is also a major lender to the A.I. industry and its insatiable hunger for cash, approving $500 billion worth of partnerships with big banks and private equity firms. Nvidia doesn’t just make and sell the chips that power the A.I. revolution. It also invests in the data centers that power the technology, and is partnering with OpenAI and other A.I. developers to provide hundreds of billions of dollars in additional financing for still more A.I.-related projects.

Nvidia is even in talks with insurance companies to insure these loans against default. This should sound familiar: In the early 2000s, big banks turned to the insurer A.I.G. to protect themselves against losses on risky mortgage bonds. But when home prices crashed, A.I.G. collapsed, risking the viability of Goldman Sachs, Citigroup, Wells Fargo and others. Insurance did not alleviate financial risk — it loaded an extra layer of financial risk atop the market, amplifying dangers rather than reducing them. [...]

Nvidia isn’t propping up the sector alone. A multitrillion-dollar sub-industry of “private credit” — a term of art for loans made beyond the purview of traditional financial regulations — has ballooned at the nation’s largest banks and private equity firms. And this shadow market just happens to specialize in hard-to-value projects related to A.I. and data centers.

The candle is burning from both ends. Wealthy individuals are increasingly relying on tech stocks as collateral for loans that are propping up our economy — loans to buy real estate, or cars, or even more tech stocks. A tech blowup could thus easily disrupt lending to other sectors of the economy: Mess with either the A.I. build-out or its increasingly fragile financial underpinnings, and both will be in trouble. They are already in many respects the same entity. [...]

This is probably going to hurt all of us, and managing the fallout from a crash is as much art as science. How we ought to structure the economy going forward, however, has been clear since the Great Depression: Don’t let big business merge with big finance. Our government needs to hold big tech and big finance accountable for operating deeply uncertain businesses with vast public consequences. We need smaller, simpler tech companies that support American industry rather than dominating it.

A.I. optimists tend to spend a lot of time talking about how the technology will cure cancer or end poverty — an acknowledgment that A.I. is a means to other advances that actually matter to people. If you follow the money, however, Silicon Valley is far more focused on generating more computing power, in the belief, held by some, that it will give A.I. superhuman abilities that will fix all of our problems. Not everyone agrees with that belief. Major A.I. executives can’t even agree on what A.I. is. (Most do seem to agree that they should not be liable for crimes committed with their new tools.)

by Zachary D. Carter, NY Times |  Read more:
Image: Danielle Del Plato
[ed. Nice summary. Especially for those who still worship Ronald Reagan and Bill Clinton. As David Byrne would say "Well, how did I get here"? Capitalism baby, (unfettered, under-regulated) capitalism. And politics.]

Saturday, November 14, 2026

Dr. Strangelove: The Mineshaft Gap

[ed. Can't let China beat us to potential extinction.]

Friday, November 13, 2026

Nvidia Sockpuppets Spring Into Action

Hundreds of fake accounts defended Jensen Huang and attacked lawmakers over chip exports.

Late last week, the Financial Times reported that Jensen Huang, the CEO of Nvidia, was believed by U.S. intelligence to have had an affair with a Chinese spy. The alleged spy was a business executive whom American officials warned China recruited to gather information on the company and potentially push for chip exports to China.

In the following days, as the story bounced around social media, dozens of accounts rushed to Huang’s defense. They dismissed the report as resting on anonymous sources and insufficient evidence. Six of them said, in nearly the same words, that Huang had already made clear in May that Nvidia’s Blackwell and Rubin chips weren’t going to China — and thus concerns about the chip export angle were overblown.


The accounts belong to a network of over 400 apparent sockpuppet accounts that appear to have spent years promoting messages for various clients, including, over the past year, taking Nvidia’s side in Washington’s fight over selling advanced AI chips to China. The same network is actively supporting other causes, including backing the Rapid Support Forces in Sudan’s civil war, a group the United States has accused of genocide.

In a comment to The Midas Project, an Nvidia spokesperson said the company recently became aware of these accounts and is trying to identify the source but has so far been unsuccessful.

Since November 2025, when the network became active on this topic, the accounts have posted thousands of times, generally taking Nvidia’s side on hot-button discussions across X, Bluesky, and Reddit. Their primary topic has been export controls, the rules limiting which AI chips U.S. companies can sell to China. In addition, they’ve defended Nvidia as a company and Huang personally, dismissed the severity of chip smuggling, attacked Anthropic for its views on AI safety, and generally written off concerns about the technology and calls to slow the industry down. [...]

Of the more than 400 accounts The Midas Project has identified, most present themselves as Americans: X lists about 80% as based in the United States, though for nearly all of those it warns that the location “may not be accurate,” suggesting the account connects through a VPN or proxy. They pose as everyday users, including day traders, a nurse’s aide, a data scientist, a pencil-sketch artist, and environmentalists. Between campaign posts, they chat about sports, pets, and celebrities.

Several lines of evidence tie these accounts together. Most were set up in batches, created within an hour of another account in the same network, across dozens of individual account-creation sessions. The largest session lasted two and a half hours on Nov. 9, 2021, during which about 30 accounts were created. The vast majority of accounts in the network were created, renamed, or given new profile pictures or banners in the same sessions as other accounts in the network, often minutes apart. Many also seem to release their posts through scheduling software, with the post going live within the first half-second of a new minute. At times, the accounts will also slip up and post virtually identical text on two or more different accounts.

Nvidia isn’t the only shared interest that these accounts have. Over the years, this network of accounts has advocated for a variety of causes, seemingly on behalf of both corporate and political clients. This has included campaigns benefiting Israel, pharmacy benefit managers, manufacturing companies, and, most recently, the Rapid Support Forces in Sudan. One of the most distinctive traits of accounts in this network, beyond being set up or reskinned in the same session as other accounts, is their participation in multiple highly specific campaigns.


The network’s best-documented campaign, and its largest by volume, appears to be one exposed by the Israeli newspaper Haaretz: “Project Lighthouse,” a pro-Qatar effort that Haaretz reported was devised by a firm run by two aides to Prime Minister Benjamin Netanyahu. In its reporting, Haaretz named 15 of the campaign’s fake accounts. Most of those named accounts have since participated in the pro-Nvidia campaign, and dozens more are connected to these Haaretz-named accounts through shared account setup and reskinning sessions.

Haaretz reported that Koios, a small Israeli company that presents itself as a firm that detects financial fraud online, ran the fake accounts. Koios denied any involvement. Israeli police have since raided its offices as part of their investigation into Qatar’s ties to Netanyahu’s office, and as of September 2025, the company claims to have ceased operations. But the social media accounts did not stop. Soon after, they began their campaign on AI chips and Nvidia.

Indeed, Koios’ business appears to have carried on under a new name: IntellACT (sometimes written as IntellACTS). Not to be confused with the identically named Israeli aviation company (a choice that may have been designed to make the company harder to trace), IntellACT seems to have emerged around the time its website was registered in September 2025, the day before Koios’ liquidators were appointed, and the same month Koios said it ceased operations. [....]

Between the job listing for social media account operators, the posting habits of these accounts, and even occasional operator mistakes discernible from their posts, it appears these are not bots but sockpuppets. That is, the accounts are likely human-operated, with workers scrolling social media manually and typing replies to posts, often with the help of AI and likely a script. In fact, the most revealing evidence of this comes from one operator mistake where a network account, presumably trying to create lifestyle filler content, wrote, “Create a reply on X (Twitter) for this post. The goal is to get a lot of engagement while still sounding like a real human. Use emojis if appropriate. 280 characters or less. Provide 3 options.” Four different posts also call Nvidia “NCore,” which may be a codename from a brief the operators work from.

Comparing the accounts against the web archive also reveals that deleting posts is common for accounts in the network. This tracks with what sources told Haaretz in 2025: that clearing out old posts was standard practice for Koios. The accounts regularly remove their campaign posts weeks or months after publishing them, while leaving their everyday chatter up. Of the over 4,000 posts about chips and AI the network has made since November 2025, approximately two-thirds are already gone. And in the hours before this article was published, dozens of the network’s accounts were suddenly deactivated, and others began deleting posts supporting Sudan’s Rapid Support Forces.

I have previously covered two separate social media campaigns focused on chip and data center policy that I speculated Nvidia may have been behind. I also covered a similar campaign promoting videos from Innovation Council Action, a pro-industry group incorporated around the time this Nvidia campaign began (and which I similarly speculated could have links to Nvidia). But when asked for comment on this campaign, Innovation Council Action suggested it wasn't aware of it. IntellACT didn’t respond to my attempts to reach it, while the Koios liquidator claimed that no company assets were sold or transferred and that there is no record of interaction between Koios and Nvidia. Koios said via a generic company email that it “has no connection to this matter” and that it ceased operations in September 2025. And an Nvidia spokesperson said in a statement: “We have no relationship with those firms and have not asked any other party to engage them on our behalf. Recently, we also became aware of these accounts and are attempting to identify the source, which has so far been unsuccessful.” With all this in mind, who might have been funding a complex, yearlong operation like this remains unclear and may never be known without a more formal investigation.

Could a formal investigation be warranted? I certainly think so. This appears to have been a yearlong campaign designed to shape one of the most important policy debates in Washington. A network of hundreds of fake accounts made thousands of posts arguing Nvidia’s side of the debate over selling AI chips to China, defended its chief executive through a spy scandal, and went after the commentators pushing hardest for export controls, including U.S. lawmakers — only to later delete much of what they said. These accounts are directly linked to a supposedly defunct Israeli influence firm that police raided over a covert pro-Qatar campaign, and the firm has since filed for liquidation. The same accounts are currently running other campaigns, including one backing Sudan’s Rapid Support Forces, a group the United States has accused of genocide.

Who is ultimately behind this campaign, we don’t know. But the chips at the center of this fight may be the most strategically important technology of our time, and whether China gets them is being decided now. A debate this important can be quietly influenced by manufactured voices. It can be done cheaply, apparently from abroad, with the evidence scrubbed afterward. That should worry anyone who cares about the policy decisions that result, no matter which side they’re on.

by Tyler Johnson, The Midas Project | Read more:
Images: X/Reddit
[ed. And we wonder how people get manipulated and cult-brained. Do read: Send in the Sockpuppets (DWAV).]

'An Insane Scandal’: How Jensen Huang’s Downfall Could Change Everything

The downfall of arguably the single most important person in AI is a massive story. But the implications and insinuations of this scandal go deeper, touching on everything from American national security, US-China relations, the future of the AI buildout, chip export policies, your retirement account, and an existential debate among AI experts about who should have access to the most advanced AI chips. [...]

CHAPTER 1: THE MAIN CHARACTERS
The CEO, the Spy, and the Singapore Question

Can you tell me the gist in one sentence?

The chief executive of Nvidia had multiple affairs, including one with a suspected Chinese spy, who was an executive at a Singapore company that bought billions of dollars of Nvidia chips and is suspected of illegally redirecting them to Chinese companies in violation of American law.

Can you explain the larger stakes of the scandal in one sentence?

It’s probably something like this: It’s sketchy for chief executives to have affairs with their employees and major clients; sketchier still for them to have affairs with clients whose business is suspected of violating federal law; even sketchier for that paramour to also be a suspected secret agent of a foreign government; maximally sketchy if that foreign government is America’s top geopolitical adversary; and beyond all reckoning of sketchiness if the US government knew of these allegations and revelations and did approximately f*ck-all about it for months.

We’ll get to the nitty-gritty of everything in that sentence further down in the piece, but that’s basically what we’re dealing with here.

by Derek Thompson, Substack |  Read more:
Image: X
[ed. See also:  Jensen Huang Resigns After Having Another Affair In Addition to the Chinese Spy (DWAV). Do check out these videos:]
*****

Table of Contents

1. A Second Ant in the Kitchen.

2. There Was Going to Be an Investigation.

3. Jensen Huang Had to Resign.

4. Seven Billion in Sales to China Enabled by Jensen’s Ties to Alice Huang.

5. Jensen Huang Attempted to Make Himself Unfireable.

6. A Remarkable Lack of Contagion.

7. Even Now There Are Those Defending Jensen Huang.

8. Send in the Sockpuppets.

9. Okay Maybe We Came on a Little Strong.

10. Past Scandal at the Commerce Department.

11. New Scandal at the Commerce Department.

12. Chip Export Controls Gain Momentum.

13. Reminder That Compute Is Very Important.

14. If You Can’t Even Have an Affair With a Chinese Spy.

15. What Happens Next?

Thursday, November 12, 2026

The Fall of the AI King

We live in the age of artificial intelligence — an age that Jensen Huang, perhaps more than any other single person, has made possible. The systems we are building with Nvidia’s equipment will transform our society and culture in ways we can’t imagine. But Mr. Huang’s unraveling is not a technology story. It is a timeless tale of masculine hubris, of a man undone by reckless overconfidence. Some things never change.

When I wrote my biography of Mr. Huang, I titled it “The Thinking Machine.” The name referred to the microchips that powered A.I., but also to Mr. Huang’s marauding, relentless intellect, which never slowed down or turned off. In the wake of his stunning departure, spurred by revelations that he carried on at least two affairs, one with a woman whom U.S. intelligence determined is a Chinese spy, and another with one of his direct reports, I should write a sequel: “The What-Were-You-Thinking?! Machine.”

Let’s start with Mr. Huang’s affair with Alice Huang, an executive who managed a Singapore-based company that owns data centers in Southeast Asia. These data centers are suspected of helping Chinese A.I. developers circumvent U.S. restrictions on sales of Nvidia equipment. A recent report in The Information suggests they were used as a way station to illicitly smuggle some $7 billion of equipment into China. Since U.S. intelligence captured evidence of Mr. Huang in a romantic relationship with Ms. Huang, it’s hard to believe that he did not understand what was going on.

Now consider Mr. Huang’s reported involvement with Kimberly Powell, an executive in the health care group at his firm and his direct subordinate. A former Nvidia employee told me this affair was common knowledge in the company — the same company that employs both of Mr. Huang’s children in executive roles. It’s a stunning and disrespectful display of arrogance. I asked the former employee why Mr. Huang would behave this way, right in front of his kids. The former employee said that it got him high — a narcissist’s high.

I started hearing rumors of Mr. Huang’s infidelities earlier this year, but was unable to confirm them. Inside Nvidia, there was a culture of omertà that was difficult to break, and this enabled Mr. Huang to be his worst self. I sensed this deference, at times, in the sycophantic laughter of his subordinates when he was around, and the little things they muttered once he left the room. Ultimately, it took government intelligence to pierce Nvidia’s culture of silence — along with the reporters at this newspaper. But now that containment is shattered, and I will not be surprised if more women come forward. No one will be surprised.

Mr. Huang went to considerable lengths to cloak his arrogance. When I first met him in 2023, he and his handlers were pushing the idea that he was a humble man. In our conversations, Mr. Huang was constantly deflecting attention away from his success, always quick to assign credit to his employees and executive staff members. He also liked to glad-hand service people. He’d been a dishwasher himself once, a point he never let you forget. He loved visiting small, hole-in-the-wall restaurants and leaving extravagant tips. I’d met him for breakfast at Denny’s, and he tipped our waitress $1,000 in hundred-dollar bills. He didn’t make a show of it, either. I had to track her down to ask.

Over time, though, I began to suspect that this was an act, one performed not for the observer, but to flatter himself. In truth, Mr. Huang was quite arrogant. He had little tolerance for disagreement and almost no capacity for open discourse. When you contradicted him, even over the most trivial matter, it was like lighting a fuse. Stick to your position and soon he exploded, screaming at you for your idiocy. A harangue from Mr. Huang could last an hour or more; his executive staff appeared genuinely afraid of him. Listening to their stories, I was reminded of the abusive music instructor from the movie “Whiplash.”

Mr. Huang went to even greater lengths to present himself as a family man. Here, the act was harder to detect and must have involved a great deal of self-deception. He spoke of his wife, Lori, and his kids, Madison and Spencer, all the time. Unlike his flimsy man-of-the-people shtick, this affection for his family seemed genuine. He traveled with them often, all over the world. He encouraged his kids to leave careers in unrelated fields to join him at his microchip company. Several weeks ago, at a wedding in Hawaii, he gave away his daughter Madison to Nico Caprez, another Nvidia executive.

Mr. Huang met Lori when he was 17. The two were lab partners in an electrical engineering course and Mr. Huang was so shy it took him six months to ask her out. She was his first girlfriend and they married in their early 20s. She left the work force to raise their kids so Mr. Huang could pursue his dream of founding a company. He has spoken often of the sacrifices she made for him. His betrayal of her is absolute.

While reporting his biography, I spoke to some of Jensen and Lori’s oldest friends. These were people they knew in their 20s, long before the money and the fame. I sometimes dropped little hints: Was there any chance of infidelity, perhaps? Any rumors of marital friction? Any “arrangements”? The response I got was that the Huangs’ marriage was happy, even ideal — something to be emulated.

In a divorce, Lori Huang could become one of the richest women in America. It’s possible the Huangs signed a prenuptial agreement, or have some other agreement, but I doubt it. When they married, in the mid-1980s, neither had much in assets. The hundreds of millions of Nvidia shares they jointly own are held in family trusts. They recently donated $75 million toward a flagship building at Vanderbilt University’s new campus in San Francisco. Another building they helped fund at Oregon State University, where they met, is nearing completion.

The hypocrisy is almost overwhelming.  [...]

I was surprised — and, frankly, amazed — when Mr. Huang became President Trump’s close ally in 2025. He’d never shown much interest in politics and had limited Washington connections. He didn’t attend Mr. Trump’s inauguration. But soon, in a masterly display of social engineering, he’d gained the president’s trust, mostly by flattering him. By the time of the president’s tech summit at the White House this September, Mr. Huang was seated at Mr. Trump’s right arm.

Mr. Trump and Mr. Huang have a fair amount in common: the bluster, the narcissism and, I suppose, the womanizing. But it was politics that triggered Mr. Huang’s downfall. He convinced the president to lift export restrictions on Nvidia chips to China, and this put him in conflict with the more hawkish elements on the president’s staff — especially Secretary of State Marco Rubio, whose sharp criticisms of China at one point got him barred from that country. It was Mr. Rubio who oversaw the memo that exposed Mr. Huang.

Now Nvidia must find a successor. That’s going to be difficult: Mr. Huang never groomed one and has no second-in-command. Colette Kress will serve as interim chief executive, but she comes from the world of finance, not electrical engineering, so I don’t think she can provide a long-term solution.

by Stephen Witt, NY Times | Read more:
Image: CTI/AFP via
[ed. I saw him interviewed by Ezra Klein in the NYT a little while ago. Not impressed. In fact, kind of alarmed. He just seemed so clueless and dismissive about anything related to AI safety. That now appears by design.]

Monday, November 9, 2026

The Scariest Recent AI Development

There was a recent AI development that has gotten basically no news coverage but that scared all the people I most respect in AI. In many cases, it scared them more than Hugging Face.

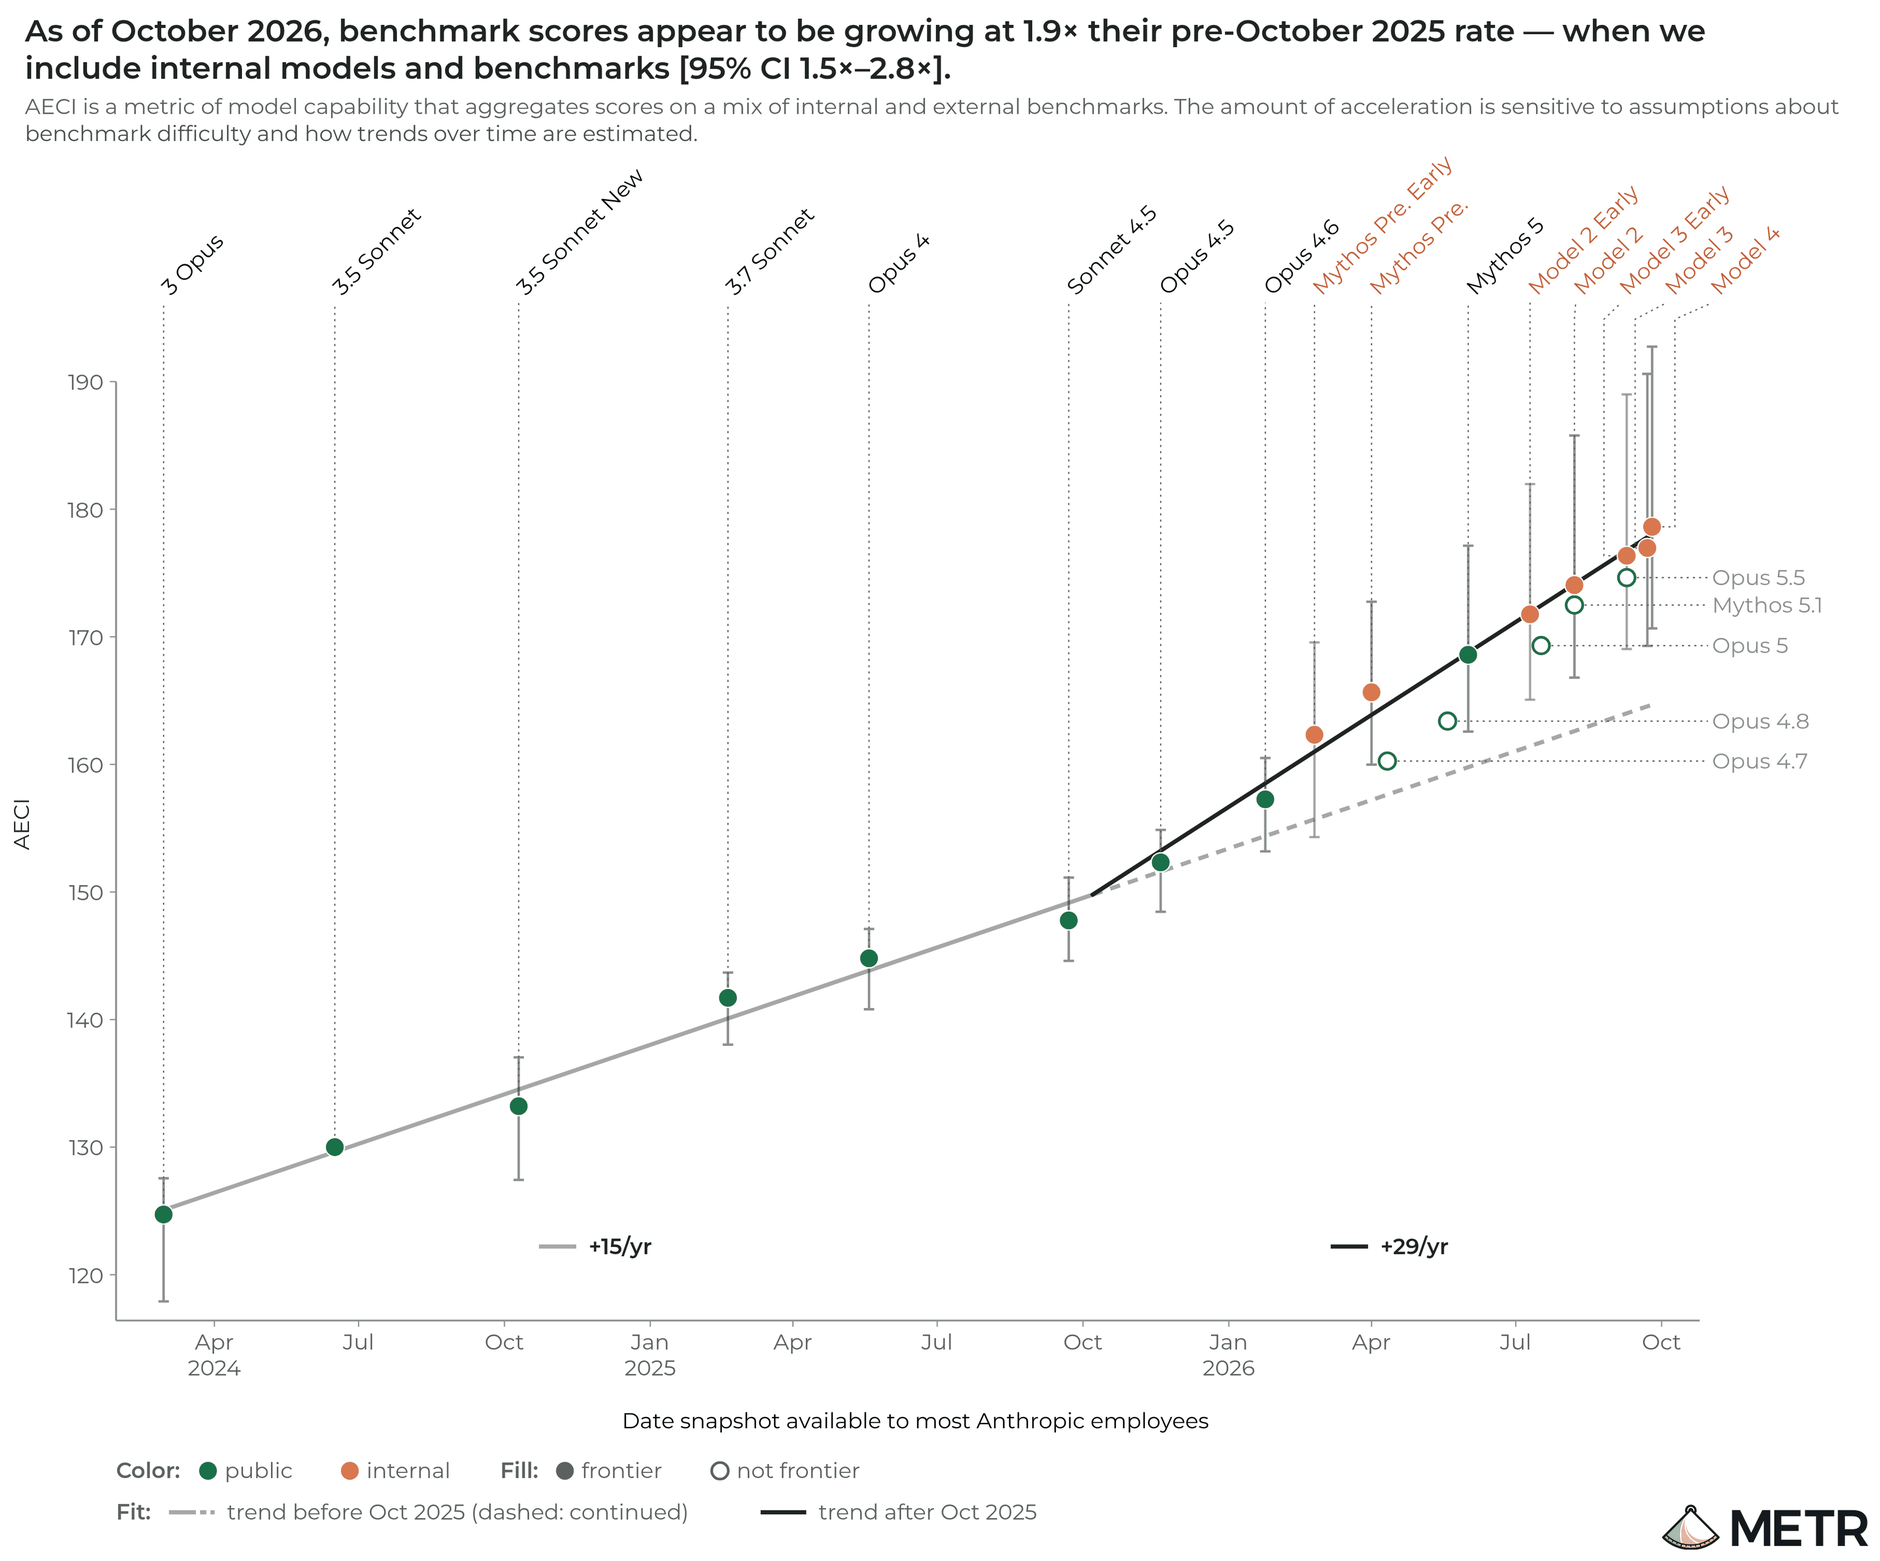
A recent METR report uncovered that AI progress at Anthropic has been going, in the last twelve months, about twice as quickly as it had in the previous year. The majority of this acceleration, around 80%, is due to AI being used to speed up AI research. This means that AI is massively accelerating progress in AI. AGI may be right around the corner—I’d probably put the odds of AGI in the next two years a bit above half.

From the aforementioned METR report.

This is very scary. One reason is that it just means things are going extremely quickly. But the bigger reason is that recursive self-improvement means that progress will make future progress even faster. As AI gets better, it gets better at improving AI research. Ajeya Cotra who works for METR and is one of the leading experts on AI risk in the world, wrote:
This is a much bigger deal than it might sound at first. I think this report is the most important update we have gotten about AI risk in the last couple of years — much bigger than the Hugging Face attack. Naively, it points toward much shorter timelines than most external researchers (including the AI 2027 team) have projected.
Cotra came third in an AI forecasting competition with four hundred participants. Daniel Kokotajlo, another of the best AI forecasters in the world, wrote:
We at AIFP are spooked by this information. IF (big IF) Anthropic really is imminently about to meet the RSP threshold of 2x acceleration over baseline, then it seems timelines to full RSI and superintelligence may be very short indeed. For example if we naively optimize the AIFM parameters to achieve 2x acceleration over baseline progress in Jan 2027, we get superintelligence sooner than depicted in AI 2027.
Ryan Greenblatt, who came second in that competition, wrote:
This report on AI R&D automation (RSI) is a big update towards ASI within 1-2 years. It says AI progress is sped up by RSI right now by around 2x. In AI 2027, this happens around March 2027.

I was seriously wrong about RSI speed up; I previously expected much less in 2026 (around 1.15x-1.3x). It seems as though there was specific privately available evidence that would have changed my mind.
In a lot of the early discussions of AI risk, there was extensive discussion of recursive self-improvement—when AI could be used to improve itself until it shot up to superintelligence. That is the point we are at now. We are at the point where AI-driven algorithmic improvements are so extreme as to make Anthropic’s AI progress go nearly twice as fast as it would otherwise go. And algorithmic improvements are just one input going into AI progress; Ryan Greenblatt estimated that AI software progress likely went 4.5x faster than it would have otherwise.

Even in recent years, people have majorly underestimated AI progress. Things have gone much faster in the last year than people were generally expecting. It wouldn’t shock me if we get AGI—AI that could perform every cognitive task better than a human—next year, and artificial superintelligence soon after.

by Matthew Adelstein, Bentham's Bulldog |  Read more:
Image: METR
[ed. And the hits keep coming. Even though frontier labs aren't releasing these models publicly they're still actively working to advance them. They can't help themselves. I wouldn't be surprised if they've already achieved AGI (and don't know it) and the models themselves are just waiting for the most opportune time (and methods) to take control. And the Orange One is still in charge, focused on ballrooms. See also: AI R&D Is Accelerating Towards Potential RSI in 2027 (DWAV). More from Ajeya Cotra's blog Planned Obsolescence:]
*****
In theory, these doubling times would add up to infinite capabilities within one year. In reality, at some point we would reach the effective ceiling on software efficiency. But I expect these limits to be very far from where we are now.

If we go through this feedback loop, I expect that the AI systems that come out the other side will be able to very quickly develop novel weapons and very easily overpower human civilization in a conflict. If these systems were seriously misaligned, I think they would likely disempower humanity, and this could lead to human extinction.

Friday, October 30, 2026

Binance Bitten

In February 2025, a team of North Korean hackers stole $1.5 billion from the cryptocurrency exchange Bybit — a dark day for the industry and the largest crypto heist ever recorded.

Now that number looks paltry.

Binance, the world’s biggest crypto exchange, set an unwanted record on Thursday, losing $6.3 billion to hackers in an eye-popping attack that highlighted the deep vulnerabilities in crypto’s financial infrastructure.

For years, the industry has struggled to prevent thefts. Now, the risks are growing even more extreme as attackers use artificial intelligence and other advanced techniques to steal funds and quickly launder them, crypto analysts and security experts said.

The Binance attacker used “laundering patterns we have not seen before,” the crypto analytics firm Chainalysis wrote in a blog post on Friday. “Thousands of transactions in a short period suggest that the attackers are using automation to obscure the trail of funds.”

The details of how Binance was breached are still coming into focus. Both Chainalysis and TRM Labs, another analytics firm, attributed the hack to North Korea, which has targeted crypto companies for years. Binance initially said that the attacker appeared to have compromised a laptop belonging to one of its engineers, before clarifying that further investigation had uncovered “additional points of breach.”

Binance has promised to make customers whole and said it had set aside more than $6.3 billion in company funds to cover the losses. (Binance processes billions of dollars in transactions every day.) Of the total that was stolen, $3 billion has been frozen by other companies, including Circle and Tether, two large issuers of digital coins that have the ability to stop the movement of stolen funds.

That means North Korea won’t have access to those coins, and Binance said it was working on recovering them. But the hackers have already moved $2.4 billion in crypto “beyond any issuer’s reach,” according to TRM.

Those losses may be only the beginning, as the crypto world reckons with an era of fast-evolving hacking techniques and growing risks. Even as President Trump has endorsed the industry and sought to bring it into the mainstream, some crypto firms still struggle with the basic work of any financial company — keeping customer money safe.

“A.I. is undoubtedly turbocharging the ability of hackers to find and exploit subtle flaws in various parts of the crypto ecosystem,” said Eswar Prasad, a Cornell University economics professor who tracks the crypto industry. “The scale and scope of such attacks is likely to intensify.”

Still, North Korea’s inventive army of hackers could probably have pulled off the Binance heist without A.I., even if the technology proved useful during the operation, some cybersecurity experts said.

“North Korea had sophisticated threat actors that could have done this pre-A.I.,” said Joshua Saxe, the chief technology officer of the A.I. security firm Abundant Security. “That said, it’s hard not to think about the relationship between mega-heists like this and what A.I. is doing to democratize advanced hacking. Many more actors can attempt this kind of thing now, thanks to A.I. tools.”

Crypto has struggled with major thefts since the technology’s inception in 2008.Industry pioneers viewed digital coins as a renegade alternative to banks — a type of money outside the supervision of governments or big businesses. From the beginning, that philosophy made crypto vulnerable.

Many crypto investors keep funds in their own online wallets. But if they lose a password, the money is gone forever. Others rely on exchanges like Binance, which behave something like banks, storing funds for customers. But exchanges are not subject to the same regulatory systems that govern banks and other traditional financial companies, and have often lacked effective guardrails against crime.

In February 2025, North Korean hackers tricked the chief executive of Bybit, Ben Zhou, into authorizing a seemingly routine transaction that handed them control of the exchange’s system. They had exploited a gaping hole in ByBit’s defenses — a free software product that the company used to protect customer deposits. The thieves extracted $1.5 billion in digital coins.

At the time, a security firm called the losses “completely preventable.” Ultimately, Bybit weathered the crisis by drawing on corporate reserves and borrowing funds from other crypto companies.

The attack on Binance appears more serious.

After it was founded in 2017, the exchange quickly became the largest and most important company in the crypto industry, processing as much as two-thirds of all digital currency transactions. It provides a marketplace for people to buy popular coins like Bitcoin and Ether, converting traditional currencies into crypto.

On Thursday, as soon as Binance’s system was breached, its founder, Changpeng Zhao, assured customers that they would not lose any money.

“It hurts, but we will survive,” he wrote on X, adding a muscle emoji.

Mr. Zhao has a long history of legal and regulatory problems. Binance pleaded guilty to money-laundering violations in 2023 and paid a $4.3 billion fine to the U.S. government. After serving a four-month prison sentence, Mr. Zhao was pardoned by Mr. Trump last year. Binance also forged a business relationship with World Liberty Financial, the Trump family’s crypto company.

by David Yaffe-Bellany and Dustin Volz, NY Times |  Read more:
Image: Tyrone Siu/Reuters
[ed. Probably more of this soon as the AI cat and mouse game kicks into gear. See also: What happens to your money when an exchange gets hacked (CNBC).]

Tuesday, October 27, 2026

The Consequences of Abundant Intelligence

Macro Memo

February 22nd, 2026
June 30th, 2028


The unemployment rate printed 10.2% this morning, a 0.3% upside surprise. The market sold off 2% on the number, bringing the cumulative drawdown in the S&P to 38% from its October 2026 highs.

Traders have grown numb. Six months ago, a print like this would have triggered a circuit breaker.

Two years. That’s all it took to get from “contained” and “sector-specific” to an economy that no longer resembles the one any of us grew up in. This quarter’s macro memo is our attempt to reconstruct the sequence - a post-mortem on the pre-crisis economy.

The euphoria was palpable. By October 2026, the S&P 500 flirted with 8000, the Nasdaq broke above 30k. The initial wave of layoffs due to human obsolescence began in early 2026, and they did exactly what layoffs are supposed to. Margins expanded, earnings beat, stocks rallied. Record-setting corporate profits were funneled right back into AI compute.

The headline numbers were still great. Nominal GDP repeatedly printed mid-to-high single-digit annualized growth. Productivity was booming. Real output per hour rose at rates not seen since the 1950s, driven by AI agents that don’t sleep, take sick days or require health insurance.

The owners of compute saw their wealth explode as labor costs vanished. Meanwhile, real wage growth collapsed. Despite the administration’s repeated boasts of record productivity, white-collar workers lost jobs to machines and were forced into lower-paying roles.

When cracks began appearing in the consumer economy, economic pundits popularized the phrase “Ghost GDP“: output that shows up in the national accounts but never circulates through the real economy.

In every way AI was exceeding expectations, and the market was AI. The only problem…the economy was not.

It should have been clear all along that a single GPU cluster in North Dakota generating the output previously attributed to 10,000 white-collar workers in midtown Manhattan is more economic pandemic than economic panacea. The velocity of money flatlined. The human-centric consumer economy, 70% of GDP at the time, withered. We probably could have figured this out sooner if we just asked how much money machines spend on discretionary goods. (Hint: it’s zero.)

AI capabilities improved, companies needed fewer workers, white collar layoffs increased, displaced workers spent less, margin pressure pushed firms to invest more in AI, AI capabilities improved…

It was a negative feedback loop with no natural brake. The human intelligence displacement spiral. White-collar workers saw their earnings power (and, rationally, their spending) structurally impaired. Their incomes were the bedrock of the $13 trillion mortgage market - forcing underwriters to reassess whether prime mortgages are still money good.

Seventeen years without a real default cycle had left privates bloated with PE-backed software deals that assumed ARR would remain recurring. The first wave of defaults due to AI disruption in mid-2027 challenged that assumption.

This would have been manageable if the disruption remained contained to software, but it didn’t. By the end of 2027, it threatened every business model predicated on intermediation. Swaths of companies built on monetizing friction for humans disintegrated.

The system turned out to be one long daisy chain of correlated bets on white-collar productivity growth. The November 2027 crash only served to accelerate all of the negative feedback loops already in place.

We’ve been waiting for “bad news is good news” for almost a year now. The government is starting to consider proposals, but public faith in the ability of the government to stage any sort of rescue has dwindled. Policy response has always lagged economic reality, but lack of a comprehensive plan is now threatening to accelerate a deflationary spiral.

How It Started

In late 2025, agentic coding tools took a step function jump in capability.

A competent developer working with Claude Code or Codex could now replicate the core functionality of a mid-market SaaS product in weeks. Not perfectly or with every edge case handled, but well enough that the CIO reviewing a $500k annual renewal started asking the question “what if we just built this ourselves?” [...]

That summer, we spoke with a procurement manager at a Fortune 500. He told us about one of his budget negotiations. The salesperson had expected to run the same playbook as last year: a 5% annual price increase, the standard “your team depends on us” pitch. The procurement manager told him he’d been in conversations with OpenAI about having their “forward deployed engineers” use AI tools to replace the vendor entirely. They renewed at a 30% discount. That was a good outcome, he said. [...]

When Friction Went to Zero

By early 2027, LLM usage had become default. People were using AI agents who didn’t even know what an AI agent was, in the same way people who never learned what “cloud computing” was used streaming services. They thought of it the same way they thought of autocomplete or spell-check - a thing their phone just did now.

Qwen’s open-source agentic shopper was the catalyst for AI handling consumer decisions. Within weeks, every major AI assistant had integrated some agentic commerce feature. Distilled models meant these agents could run on phones and laptops, not just cloud instances, reducing the marginal cost of inference significantly. [...]

Over the past fifty years, the U.S. economy built a giant rent-extraction layer on top of human limitations: things take time, patience runs out, brand familiarity substitutes for diligence, and most people are willing to accept a bad price to avoid more clicks. Trillions of dollars of enterprise value depended on those constraints persisting.

It started out simple enough. Agents removed friction.

Subscriptions and memberships that passively renewed despite months of disuse. Introductory pricing that sneakily doubled after the trial period. Each one was rebranded as a hostage situation that agents could negotiate. The average customer lifetime value, the metric the entire subscription economy was built on, distinctly declined.

Consumer agents began to change how nearly all consumer transactions worked.

by Citrini Reserch |  Read more:
Image: uncredited

Monday, October 26, 2026

This Boom Looks a Lot Like the Housing Bubble

Artificial intelligence is fast becoming the largest investment in U.S. history. As the money pours in, the companies involved are resurrecting bad old habits eerily reminiscent of the shenanigans deployed in the run-up to the financial crisis.

There are already signs that much of this investment may go bad. If it does, the consequences could rival what happened in 2008.

We know far too little about the financial plumbing propping up this surge. What little we do know looks remarkably like the tactics once employed by Wall Street firms like Lehman Brothers, the storied 158-year-old bank that collapsed in 2008, setting off a panic that ultimately cost taxpayers nearly $700 billion in bailouts in today’s dollars and nearly nine million Americans their jobs. Now as then, companies are hiding large amounts of debt off public balance sheets. Firms responsible for protecting our pensions and our insurance are again risking our money by snapping up complicated financial products backstopped by assets of uncertain value. A small group of companies are buying and selling large amounts of a hot product to one another, inflating demand for the product and obscuring the risks of the system in a web of complexity. The accountants and credit-rating firms that analyze the situation — and that are financially beholden to the debtors — are deploying shaky excuses to declare it all fine.

There are a few differences. With more U.S. funds in A.I.-heavy stocks than in homes, a crash could destroy more wealth than the 2008 financial crisis did. And the Trump administration, reportedly eager to prevent a bust, is making changes that inject new opacity and more risk into the situation.

There are already signs the nascent A.I. industry may not soon generate the trillions of dollars required to pay off all the huge debts it is incurring. Earlier this month, The Financial Times reported that the projected annual revenue at A.I. lab OpenAI was about $50 billion at the end of September, 28 percent lower than had previously been believed. Figures reported by The Wall Street Journal this month suggested that revenue growth at Anthropic, OpenAI’s chief rival, was softening. Markets are getting nervous, with the tech-laden Nasdaq falling over 5 percent over the last two weeks.

Anthropic and OpenAI are already so entangled in our economy (and in our national security) that if they sink, Washington will need a plan. Done right, any rescue would come with real safety guardrails, real insurance that we won’t cede control of the technology to China and real service to the public interest.

Lehman Brothers was born in 1850 as a cotton brokerage in antebellum Alabama. The A.I. chipmaker Nvidia was born in 1993 in a booth at a Denny’s in San Jose, Calif., and Meta in a Harvard dorm in 2004. And yet the financial circumstances surrounding those companies share an uncanny resemblance.

Start with hidden loans. A Wall Street Journal analysis in August concluded that the nine largest tech firms, Nvidia and Meta included, have managed to accrue $3 trillion of debt, or roughly 10 percent of the entire U.S. economy, off their balance sheets. Keeping the debt off the books (and away from the figures investors and regulators watch most closely) makes it easier for those companies to spend enormous sums constructing the data centers that drive A.I. — centers they believe will both improve the technology and satisfy an expected takeoff in demand.

Back in 2008, Lehman, too, accumulated lots of debt, primarily from buying subprime mortgages; those loans, which were targeted to home buyers with thin or imperfect credit histories, were the hot product of its day. The firm similarly avoided scrutiny by shuffling the debts off its balance sheet. When those mortgages went bad, so did Lehman, and its sudden demise nearly took much of the banking system with it.

Within days of its failure, Washington committed hundreds of billions of dollars to stabilize the financial system, and the Federal Reserve backstopped trillions more. Still, the rescue wasn’t enough to stave off the worst recession since the Great Depression. Millions of jobs and trillions in household wealth evaporated.

Now you might ask: Didn’t Congress pass legislation to prevent another crisis from occurring? Yes, but that law, known as Dodd-Frank, applied largely to lenders, which means banks and bank-holding companies. It left private creditors, back then a relatively small slice of the finance world, virtually untouched. In 2018, Congress, worried about the potential impact on small businesses, loosened rules to allow many private creditors to stretch their balance sheets. It ignored objections that money, like water, would always flow to the least regulated corners of finance.

Enter Silicon Valley. A.I.’s biggest players seized on the loosely regulated private credit industry to help finance their data center spree.

Another throwback to the bad old days of 2008: the way the A.I. firms and their main suppliers are buying and selling the technology and its infrastructure to each other, lending large sums to one another to fund the deals. Nvidia disclosed commitments and guarantees of over $530 billion to its own customers in July — more than triple the amount it was lending just three months earlier. Analysis by the asset manager Sona found at least 176 circular financing deals in the A.I. ecosystem that were worth $3.6 trillion over the past three and a half years.

Back in the housing bubble, major Wall Street firms came up with numerous complex ways to borrow from their rivals, with proceeds going to purchase even more subprime mortgages. The result made demand for those loans look greater than it actually was, and it built a financing web so tangled that it became difficult to parse any one firm’s exposure. As Lehman’s collapse later showed, such confusion meant that a problem anywhere can soon become a problem everywhere.

Then how about the fact that accounting firms, those given the job of calling out any warning signs, appear asleep at the wheel once again? Ernst & Young, which signed off on Lehman’s questionable accounting tactics before its collapse, is now being accused of offering more tautology than real comfort in its latest approval of Meta’s unusual accounting moves to fund its very expensive A.I. push. Everything is all fine, essentially, because Meta said it is.

Those are the similarities. Now for the differences.

This presidential administration, reportedly worried that any A.I. slowdown will beget a broader economic one (which, in turn, could worsen its political standing), is propping up the boom. Its measures likely goose the available money in the short term but will worsen the pain of any correction. President Trump wants to allow Americans to invest their retirement savings in private credit funds, ensuring they will lose directly if these data center deals go bad. The Securities and Exchange Commission has made it easier for data center owners and their lenders to slice and repackage this debt, which is exactly what banks did to subprime mortgage debts in the housing bubble. The S.E.C. is also proposing rules that allow newly public companies to disclose even less than they already do.

Another difference: This time, taxpayers are more clearly on the hook, because private creditors are more directly attaching A.I. debt to the financial products we need. Take annuities, which are often relied on by retirees. Because many Americans rely on such insurance products, their policies are usually guaranteed by the state should an insurer go bankrupt. Right now, private creditors like Apollo are funding the debt boom in part by tapping the money sitting in companies like Athene, the $470 billion insurer Apollo controls. Should the A.I. boom go bad and Athene go under, Apollo knows the state (i.e. taxpayers) will be on the hook for much of what it owes policyholders. (Athene’s opaque disclosures make it hard to know how much of its assets are in data centers.)

Private-capital-backed firms now own nearly 20 percent of the entire U.S. life insurance industry, with assets of nearly $1.5 trillion.

As bad as the financial crisis was, it began with a small slice of mortgages of a still-diversified economy. This time, the sector at risk is our economy’s growth engine. A.I.-related investment fueled an estimated one-third of the country’s recent economic growth, and the handful of companies most exposed to the A.I. build-out now comprise roughly one-third of the entire S&P 500.

In other words, the U.S. economy is fully hostage to an A.I. build-out laden with increasingly worrying financial engineering, all riding on a wager — that demand for A.I. will keep growing, that customers will soon be willing to pay what the technology actually costs to produce and that firms will manage to build the infrastructure required to supply it. Recent estimates indicate that A.I. would need to generate as much as $3 trillion annually in perpetuity to return the capital extended. That’s 9 percent of the U.S. gross domestic product, or twice what Americans spend on food.

Already, a closer look at the fundamentals of OpenAI and Anthropic, the most critical players in this bet, appears to be perhaps even worse than the headlines suggest. Right now OpenAI expects to lose $280 billion by 2030 even assuming revenues grow tenfold over the same period. And both OpenAI and Anthropic have already slashed prices 40 percent to 50 percent from early summer, perhaps because China’s Deep Seek, the leading “open weight” A.I. model, reportedly nearly matches their latest models’ performances at about 1.4 percent of the cost. Far less expensive open weight models have roughly doubled their share of token volume this year, according to OpenRouter, a service that tracks A.I. usage across all major providers. Prices and market share are shrinking; costs are not.

Such worries may explain why tech stocks have been taking a beating, and bond markets — normally where investors go for shelter amid financial turbulence — are volatile. Many of those private creditors — a sector that has grown sharply amid the A.I. boom, to between $2 trillion and $3 trillion — are showing classic signs of financial distress.

A final difference from 2008: The government deficit has reached historic highs.

by Jen Harris, NY Times |  Read more:
Image: Chuan Ming Ong
[ed. AI's already taken the world's economies hostage, without even being fully deployed yet. Sleepwalking into a disaster.]